海外研报
筛选
SALES COMMENTARY ONLY (NOT A PRODUCT OF RESEARCH)
What a week – not only in markets but also in sports. With the Summer Olympics set to conclude on Sunday, it’s been nothing short of
海外研报
2024年08月14日
BofA on USA Payback, not a slowdown
We expect a consensus-like retail sales report for JulyTotal card spending per household (HH), as measured by BAC aggregated credit and
海外研报
2024年08月15日
European Morning Research Summary
This summary is compiled from research reports previously published by Barclays Equity Research. A full list of all publications is available on
海外研报
2024年08月18日
US Economic Weekly Slow and steady, not fast and furious
Weekly viewpointThis week’s jam-packed data calendar delivered mostly good news. Inflation was
海外研报
2024年08月18日
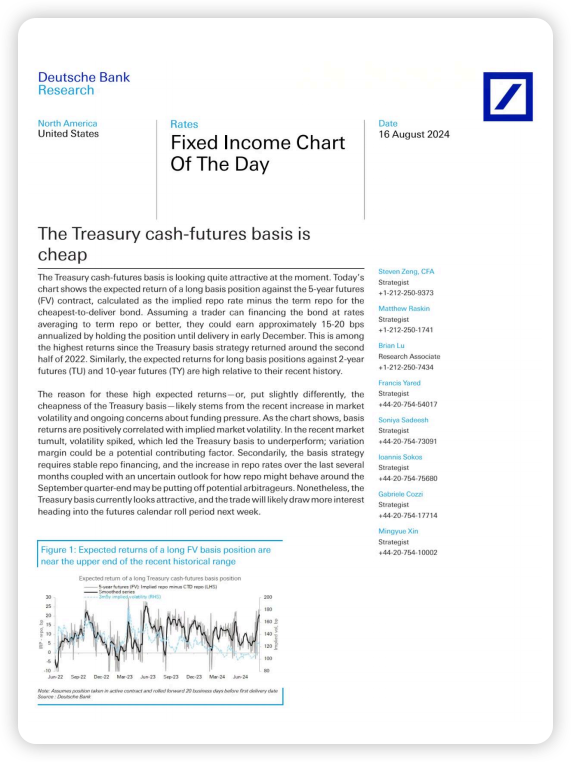
The Treasury cash-futures basis ischeap
The reason for these high expected returns-or, put slightly differently, thecheapness of the Treasury basis -likely stems from the recent increase in marketvolatility and ongoing concerns about funding pressure. As the chart shows,
海外研报
2024年08月20日
LONG CARRY, SHORT TREND
Powell's Jackson Hole speech gave a strong indication that inflation is no longer the tail risk for the Fed and that it is the health of the labour market that is now paramount. While the dual
海外研报
2024年08月29日

TECHNICAL ANALYSIS
2y UST down move stalled after defending the May 2023 trough near 3.65% but signals of significant upside are not yet visible. 2y
海外研报
2024年08月29日
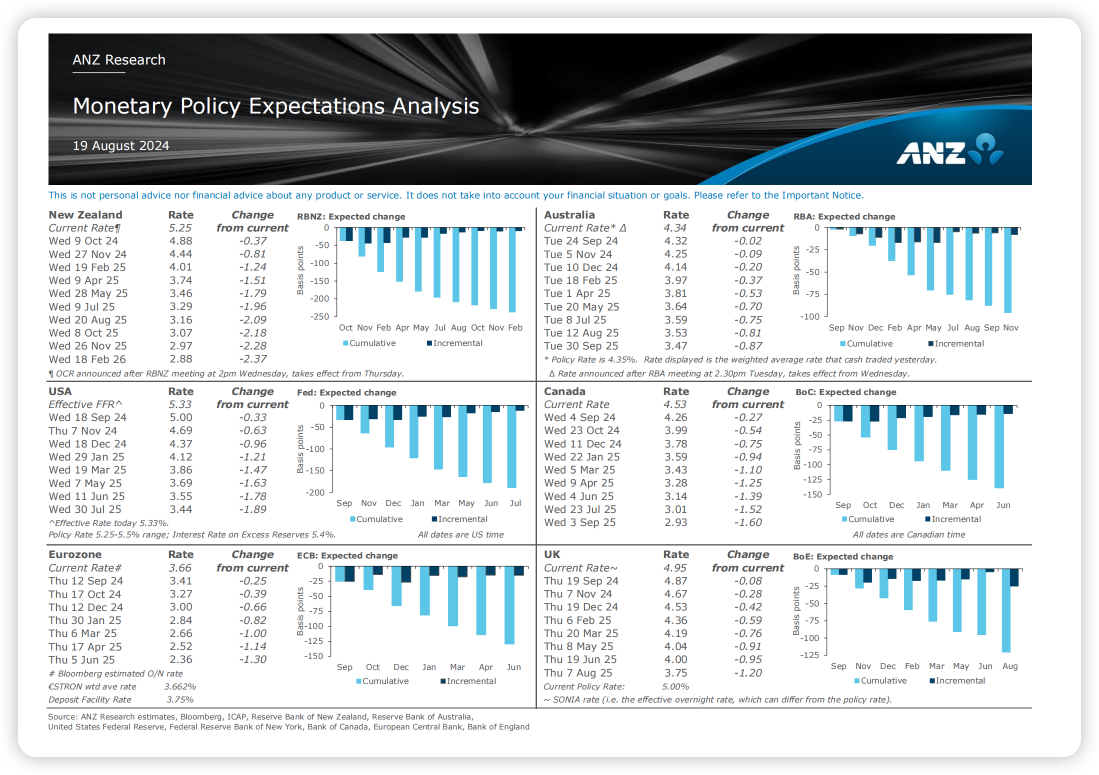
Monetary Policy Expectations Analysis
The opinions and research contained in this document (in the form of text, image, video or audio) are (a) not personal financial advice nor financial advice about any product or service; (b) provided for
海外研报
2024年08月20日

GS--China: Soft money and credit data in August
August total social financing (TSF) flows, new RMB loans, and money supply growthremained soft, largely in line with market expectations. August money and credit
海外研报
2024年09月15日

GS--Aligning our sector recommendations with the macro environment
We update our sector recommendations. We turned more“defensive” early in the summer, in response to the recent
海外研报
2024年09月15日
