海外研报
筛选
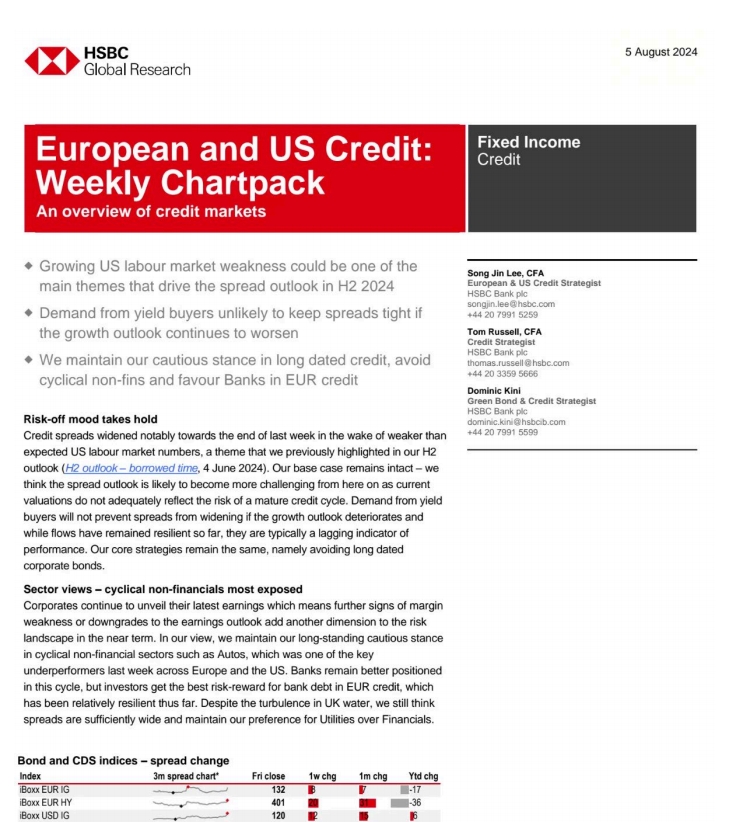
European and US Credit:Weekly ChartpackAn overview of credit markets
Credit spreads widened notably towards the end of last week in the wake of weaker thanexpected US labour market numbers, a theme that we previously highlighted in our H2outlook (H2 outlook- borowed time, 4 June 2024). Our base case
海外研报
2024年08月12日
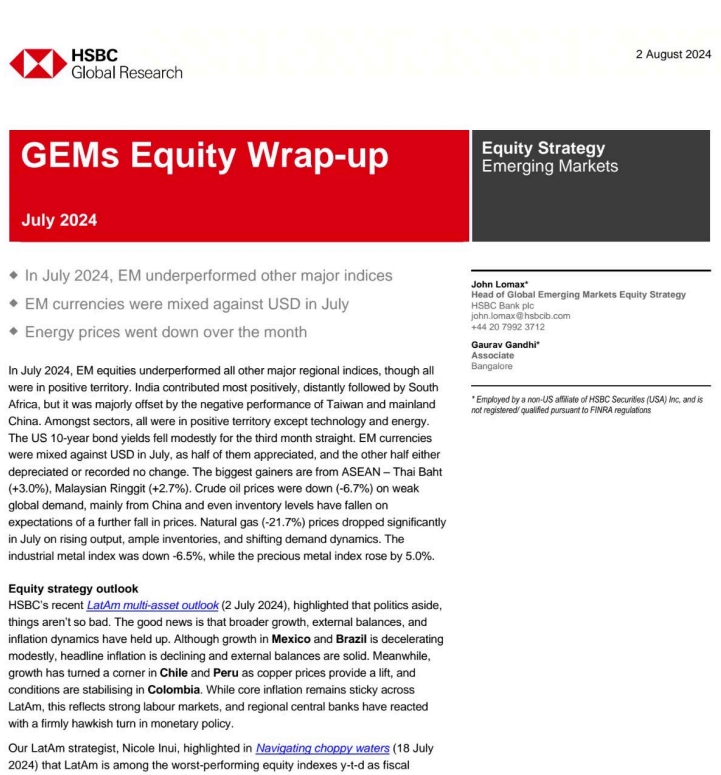
GEMs Equity Wrap-up July 2024
In July 2024, EM equities underperformed all other major regional indices, though allwere in positive territory, india contributed most positively, distantly followed by SouthAfrica, but it was majory offset by the negative performance of Taiwan
海外研报
2024年08月12日
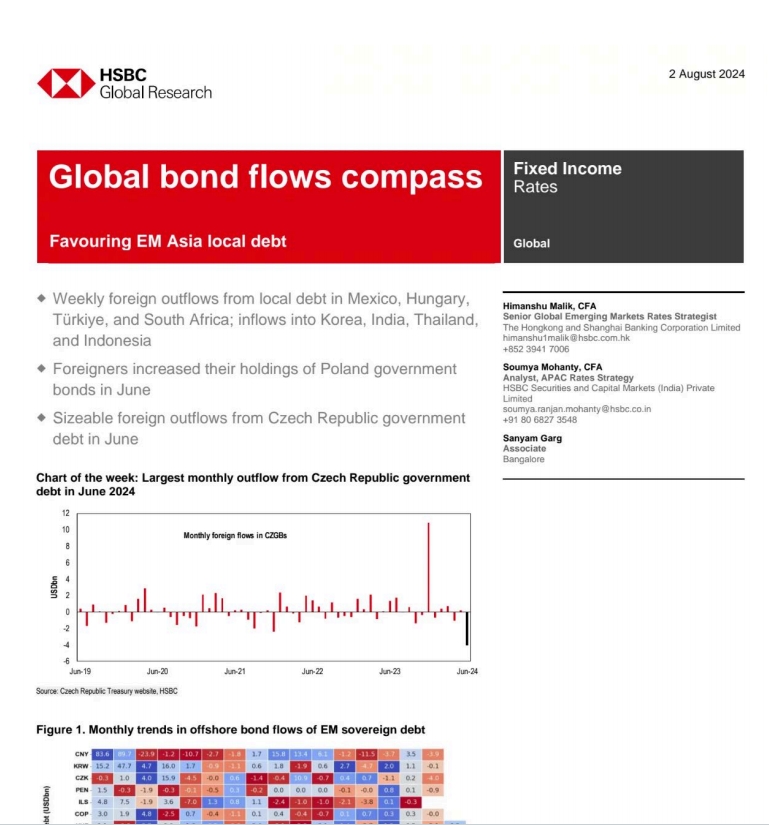
Global bond flows compass
Weekly foreign outflows from local debt in Mexico, HungaryT¼rkiye, and South Africa; inflows into Korea, India, Thailan?and
海外研报
2024年08月12日
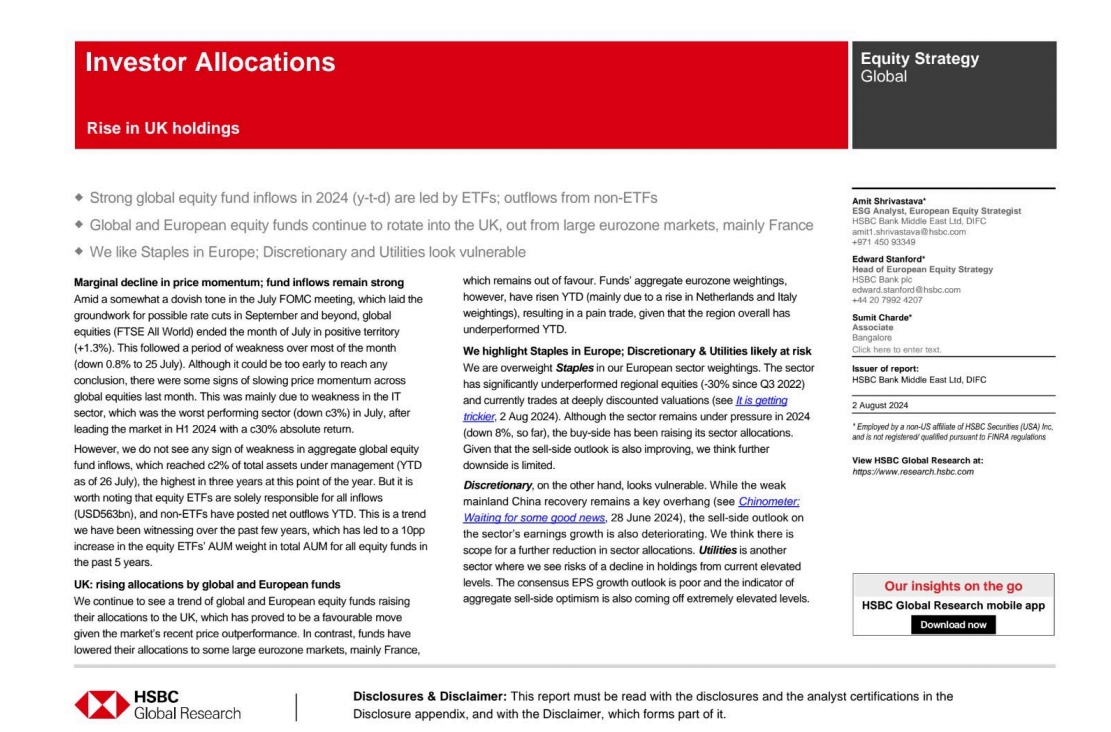
Investor Allocations
Marginal decline in price momentum; fund inflows remain strongAmid a somewhat a dovish tone in the July FOMC meeting, which laid thegroundwork for possible rate cuts in September and beyond, globalequities (FTSE All World) ended the month
海外研报
2024年08月12日
Flows & Liquidity Where have we seen most unwinding?
Momentum-driven investors such as CTAs saw a sharp unwind of long equity positions, short yen and short 10y Bund and JGB positions, while
海外研报
2024年08月12日
Global Data Watch
Recent discussion in these pages has focused on the shifting risk bias around our global narrative of sustained growth resilience, sticky inflation, and shallow
海外研报
2024年08月12日
US Weekly Prospects
Compared to last week’s event-filled calendar, the relatively quiet schedule this week gave time to pause and reflect on the
海外研报
2024年08月12日
The Weekly Worldview: The cycles advance
Last week was marked by three key central bank decisions. The BoJ hiked for the first time after ending negative interest rate policy (and specified a plan to reduce
海外研报
2024年08月12日
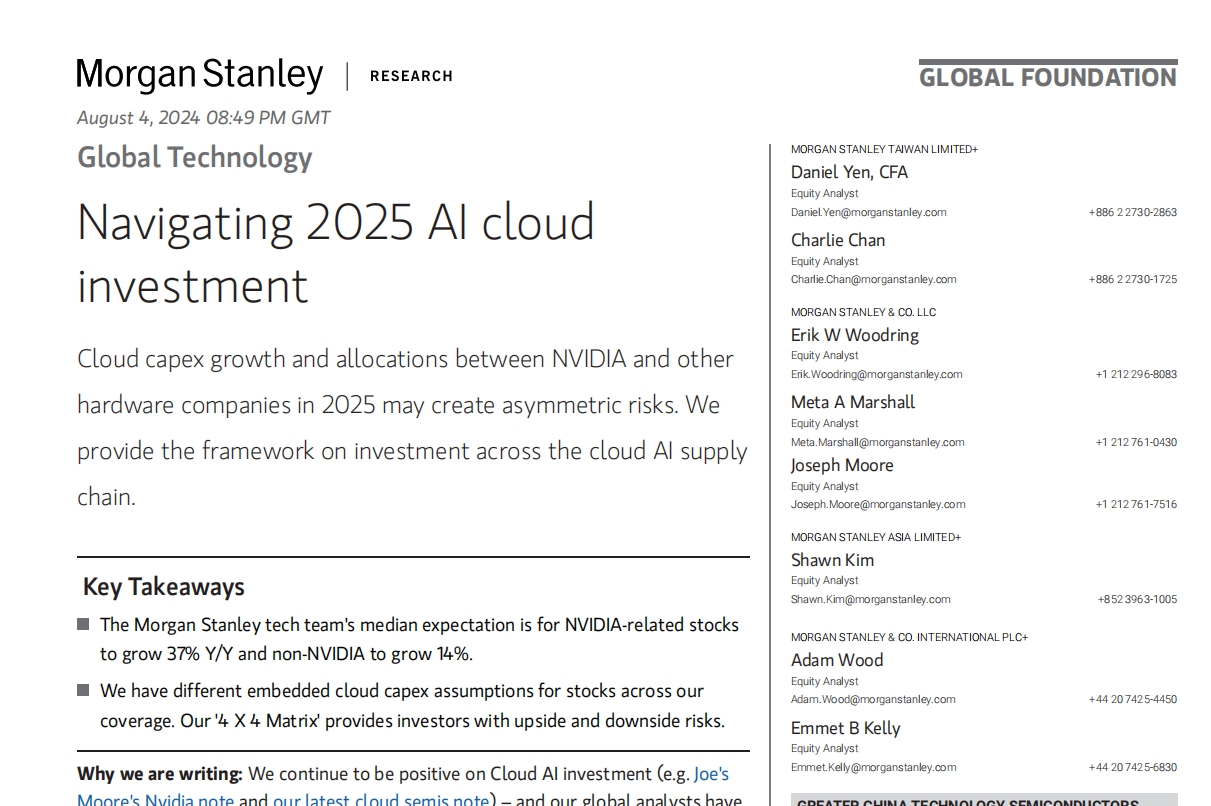
Navigating 2025 AI cloud investment
The Morgan Stanley tech team's median expectation is for NVIDIA-related stocks to grow 37% Y/Y and non-NVIDIA to grow 14%.
海外研报
2024年08月12日
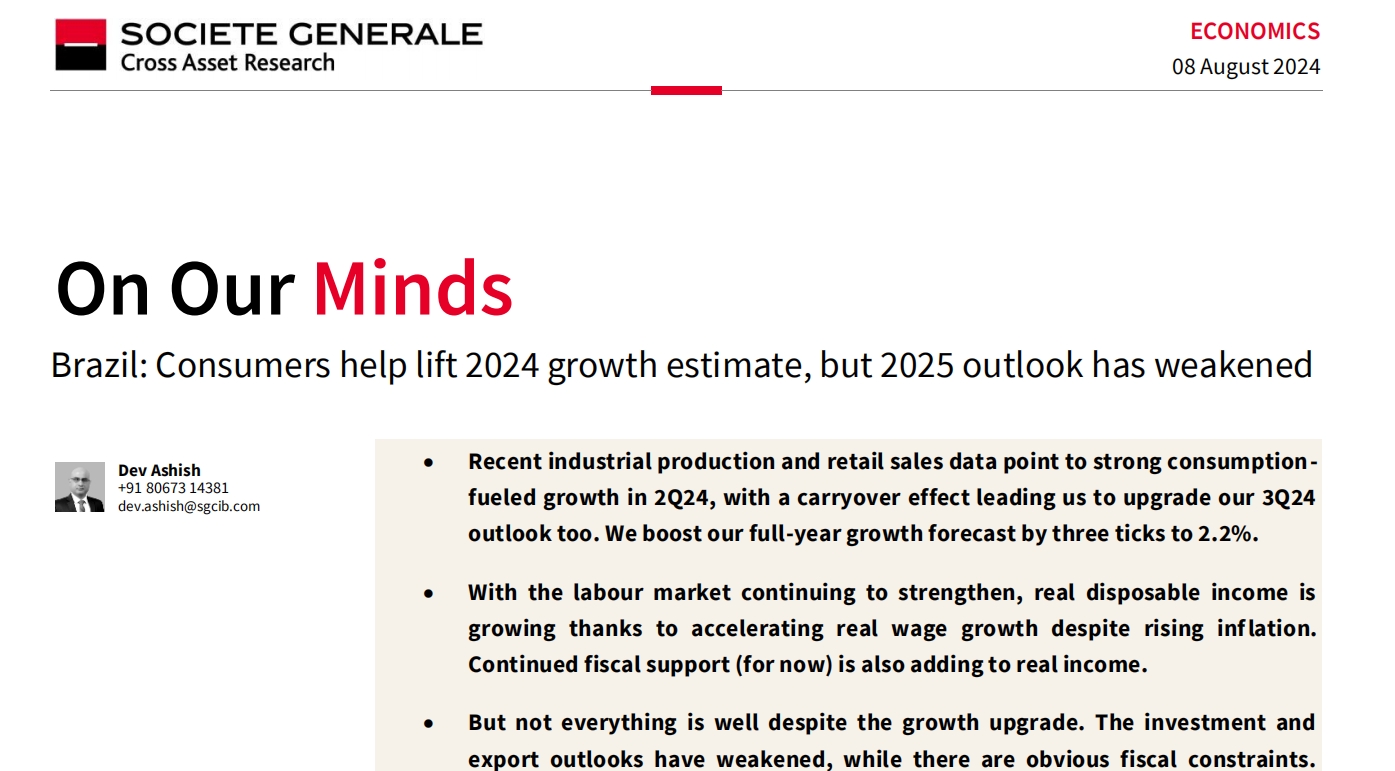
On Our Minds-Consumers help lift 2024 growth estimate, but 2025 outlook has weakened
Recent industrial production and retail sales data point to strong consumptionfueled growth in 2Q24, with a carryover effect leading us to upgrade our 3Q24
海外研报
2024年08月12日
